Energy Transition Financing for Corporates
Explore energy transition financing for corporates, from debt and tax equity to project finance, and structure fundable projects now.
– 13 min read
Explore energy transition financing for corporates, from debt and tax equity to project finance, and structure fundable projects now.

Corporates need a capital plan, not another decarbonization vision. The right financing depends on the project: balance sheet capital for simple, controlled assets, debt for predictable cash flows, project finance for larger isolated assets, tax equity for eligible US projects, and green banks or public capital to bridge gaps private lenders will not carry alone.
Corporate leaders no longer need another high-level decarbonization vision deck. They need a capital plan.
Whether you are funding onsite solar, battery storage, fleet electrification, industrial efficiency, resilient power systems, or broader infrastructure upgrades, the core challenge is the same: how do you structure energy transition financing in a way that is bankable, scalable, and aligned with your balance sheet?
That question has become more urgent as energy demand rises, project complexity increases, and capital providers become more selective. Many decarbonization projects are technically sound but still fail to attract capital because the financing pathway is unclear, the risk allocation is weak, or the project data is not investment-ready.
For corporates, project sponsors, and infrastructure teams, the real work sits at the intersection of strategy and execution: choosing the right financing instrument, packaging the opportunity in finance-grade terms, and reaching the right capital sources fast.
At Zero Circle, we see this gap every day. The market does not just need more climate ambition. It needs faster capital formation, better underwriting inputs, and more efficient matching between credible projects and relevant investors. That is exactly where a modern energy transition platform can create leverage.
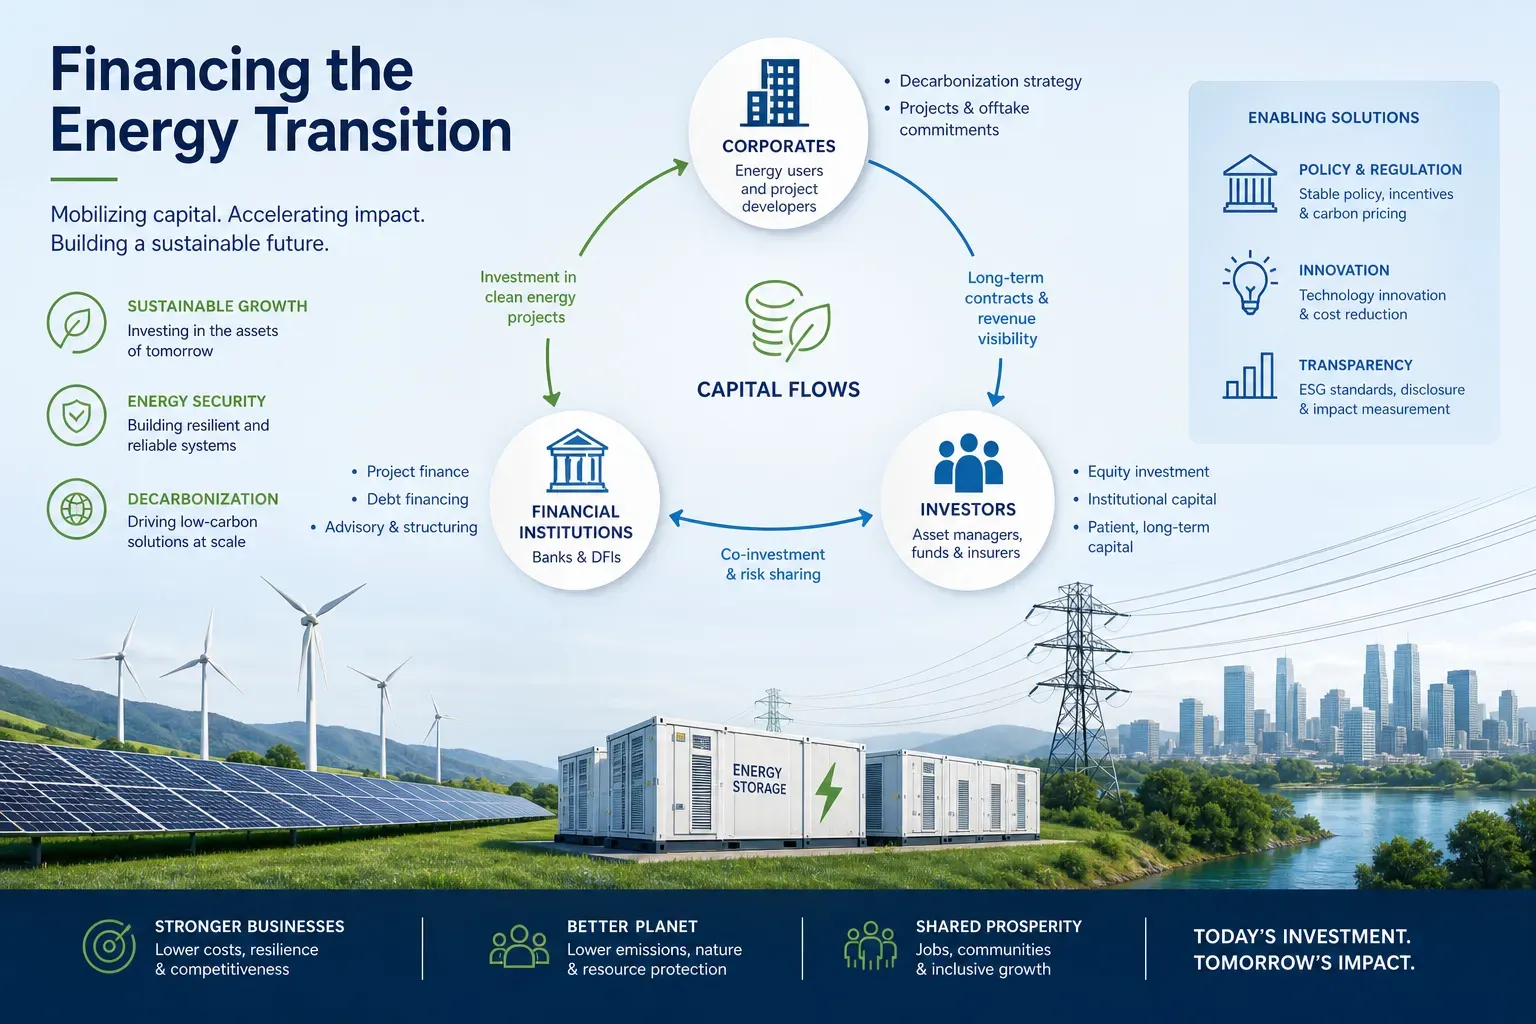
Energy transition finance is no longer limited to utilities and pure-play developers. It now sits directly inside corporate capital planning.
For enterprises, the drivers are converging:
This means financing decisions are increasingly tied to energy strategy, procurement, risk management, and long-term competitiveness.
A modern corporate energy transition plan often includes a mix of assets and interventions rather than a single project. That may involve distributed generation, storage, efficiency upgrades, electrified heat, transmission interconnection work, backup resilience systems, or low-carbon industrial retrofits. Each of those requires a different capital stack.
“Global clean energy investment reached $2.2 trillion in 2025 - more than double what flowed into fossil fuels.” - Neuberger Berman
The implication is clear: capital is available, but not evenly. The winners are projects that are prepared for diligence and structured for real-world financing conditions.
Across leading articles from asset managers, insurers, and transition-finance commentators, several themes consistently show up:
Those are valid points. But much of the existing content stays at the macro level. It explains why the transition matters without showing corporates how to make projects fundable.
That creates a content gap in four areas:
Many articles discuss “climate finance” broadly but do not clarify which instruments fit which assets.
There is not enough practical guidance on what lenders, tax equity providers, infrastructure investors, or credit committees actually need to see.
Enterprises need financing structures tied to balance-sheet priorities, procurement models, and ownership preferences.
Most content says capital is needed. Very little explains how to move from early concept to investor conversations with speed and credibility.
This guide focuses on those missing pieces.
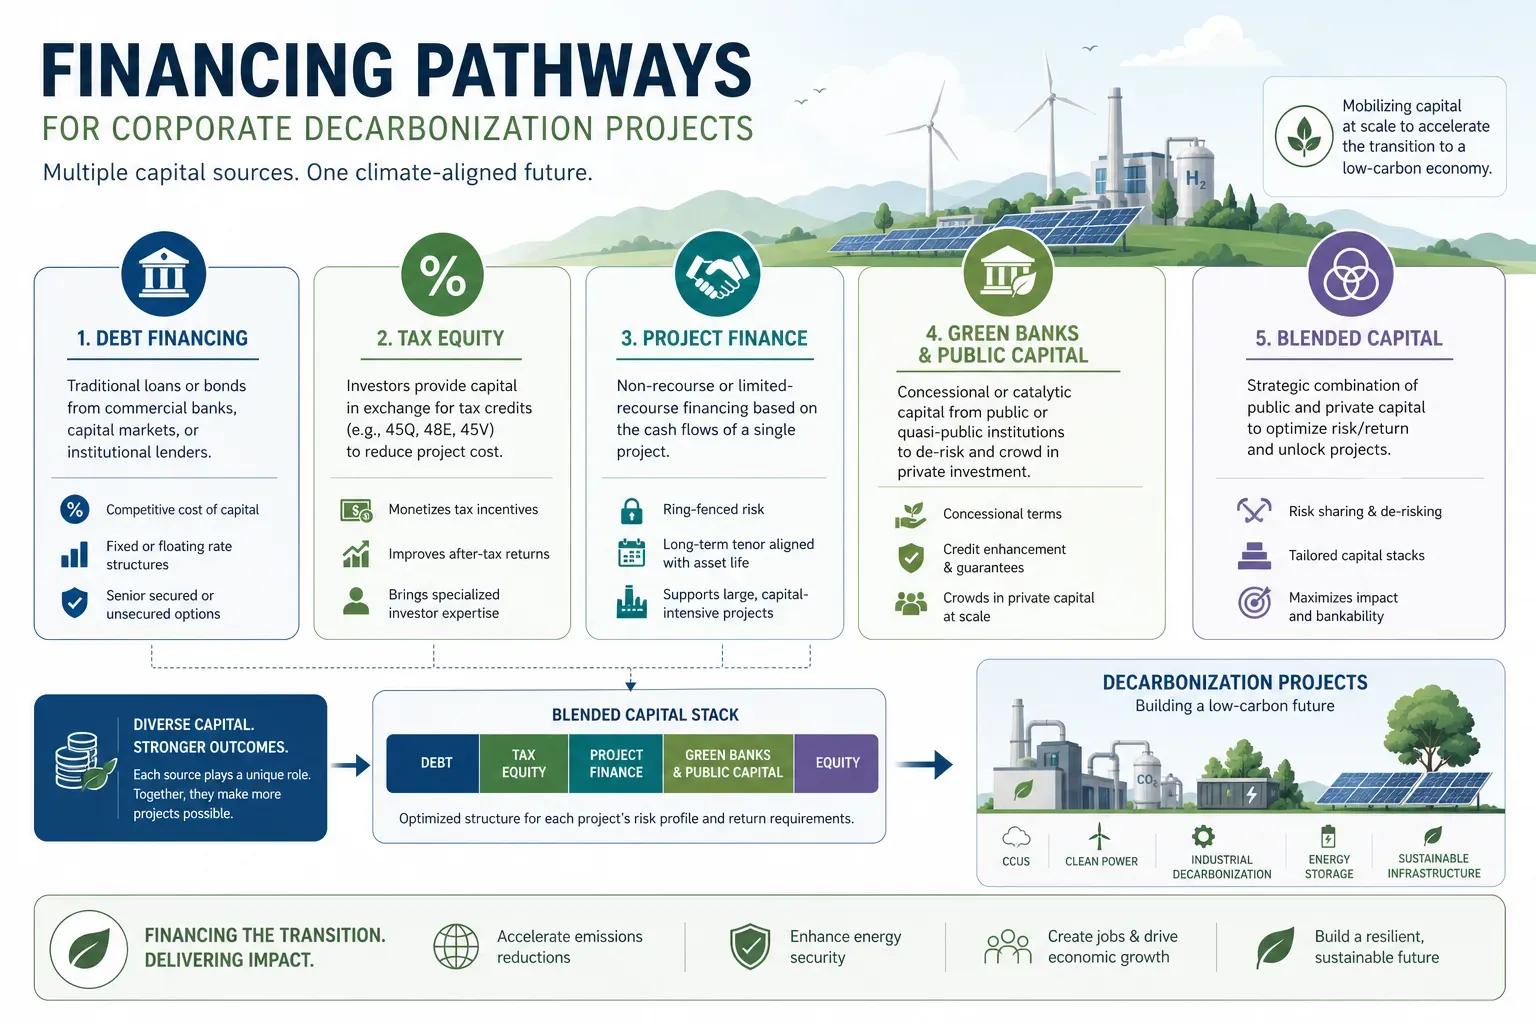
Not every project should be financed the same way. The right structure depends on project size, revenue certainty, asset ownership, technology risk, sponsor strength, and the corporate’s appetite for complexity.
| Financing pathway |
Best fit for |
Typical strengths |
Main constraints |
|---|---|---|---|
| Corporate balance sheet |
Smaller or strategic projects, energy efficiency, facility upgrades |
Fast execution, full control, simple governance |
Competes with other capex priorities |
| Corporate debt |
Established companies with strong credit |
Lower cost of capital, scalable |
Depends on leverage capacity and covenants |
| Project finance |
Large standalone assets with visible cash flows |
Off-balance-sheet potential, risk ringfencing |
Higher structuring burden, diligence-heavy |
| Tax equity |
US renewable and storage projects with tax attributes |
Monetizes incentives efficiently |
Complex, market-specific, specialized counterparties |
| Leasing / asset finance |
Equipment-based deployments |
Preserves cash, flexible tenor |
Less suitable for complex multi-risk projects |
| Green banks / public finance |
Early-stage, catalytic, or policy-aligned projects |
Can de-risk projects and crowd in private capital |
Availability varies by jurisdiction |
| Blended finance |
Emerging markets or harder-to-finance sectors |
Improves bankability through concessional layers |
Longer timelines, more stakeholders |
| Energy-as-a-service / third-party ownership |
Corporates seeking outcomes without ownership |
Minimal upfront capex, outsourced delivery |
Less control, long-term contractual tradeoffs |
For many corporates, the simplest route is still the best one.
If the project is relatively modest in size, operationally critical, and expected to generate clear cost savings, funding directly from the balance sheet can outperform more complex structures. This is especially common for:
This route works best when the corporate values speed, wants full asset control, and has internal capex availability.
But there is a tradeoff: every decarbonization investment competes with other capital priorities. If the project is treated like generic capex rather than strategic infrastructure, it may lose funding internally even if the economics are strong.
That is why the underwriting story matters even inside the enterprise. Internal investment committees increasingly want the same clarity external financiers do: payback, downside cases, implementation risks, operating assumptions, and strategic rationale.
Debt remains the backbone of much energy transition financing because many clean energy assets generate long-duration, relatively predictable value.
For corporates, debt can take several forms:
Debt tends to work best when the project has one or more of the following:
This is especially relevant for companies building portfolios of repeatable assets across locations. Rather than financing each site as a one-off, they can aggregate projects into a programmatic debt strategy.
That is where better data standardization matters. Zero Circle helps enterprises and project owners turn fragmented project details into investment-ready narratives, improving underwriting efficiency and helping lenders assess opportunities faster through finance-grade scoring and reviewable deal materials.
Project finance is often misunderstood. It is not simply “large debt.” It is a specialized structure where lenders and investors primarily underwrite the project’s own cash flows, contracts, and risk allocation rather than the full corporate balance sheet.
This model is usually best for:
Project finance is attractive when a corporate wants to:
However, it demands more preparation. Capital providers will look closely at:
A technically strong project can still fail in project finance if the documentation is weak or the risk allocation is unconvincing.
Tax equity is highly relevant in the United States for renewable energy, storage, and selected clean infrastructure projects because tax credits can represent a substantial share of total project value.
In simple terms, tax equity allows a project to bring in an investor that can efficiently use tax benefits the sponsor may not be able to fully monetize alone.
This pathway is often used for:
Tax equity can improve economics materially, but it is not a universal fit. It adds structuring complexity, requires experienced counsel and advisors, and tends to favor projects with strong documentation, scale, and certainty around qualification criteria.
For corporates, the key question is not just “Is there a tax credit?” but “Do we have the structure, timing, and counterparties to monetize it efficiently?”
If not, transferability, partnership structures, or alternative financing routes may be more practical.
Some projects are strategically important but not yet easy for private capital to underwrite on its own. This is where green banks, development institutions, export credit support, and other public or quasi-public capital sources can play a catalytic role.
They can help through:
This is particularly useful for:
The most important strategic point is that public capital often works best not as a replacement for private capital, but as a bridge to make private participation possible.
Fundable does not mean perfect. It means investable under real market conditions.
Many projects fail because sponsors focus heavily on technology and not enough on finance readiness. Capital providers are asking a different set of questions than engineers or sustainability teams.
Financiers want precision. They need to know exactly what capital is funding, what is already complete, what remains at risk, and how costs are allocated.
For corporate-led projects, this may be:
The model does not need to be simplistic, but it must be legible.
Mature technologies generally attract cheaper capital. The further a project moves toward demonstration-stage technology risk, the more selective capital becomes and the more likely blended or strategic funding support is required.
Lenders and investors care deeply about who bears which risks during construction and operation. Ambiguous contracts can destroy fundability.
A project may be exciting, but if critical permits, interconnection steps, land rights, or counterparties are unresolved, capital will price that uncertainty aggressively or decline.
Even project-level financings rely on confidence in the sponsor team. Track record, governance, reporting quality, and responsiveness all matter.
Some projects fail because sponsors ask the wrong capital source to take the wrong risk. Senior lenders do not want early development uncertainty. Equity investors may not want fully de-risked, low-return exposure. Structure matters.
Below is a practical framework corporate leaders can use.
| Project type |
Typical ownership model |
Common financing routes |
Key bankability issue |
|---|---|---|---|
| Energy efficiency retrofits |
Corporate-owned |
Balance sheet, green loan, equipment finance |
Measurement and verification of savings |
| Onsite solar |
Corporate-owned or third-party owned |
Lease, PPA, project finance, tax equity |
Site complexity and contract structure |
| Battery storage |
Corporate or SPV |
Debt, tax equity, project finance, private credit |
Revenue stacking and dispatch risk |
| Fleet electrification |
Corporate-owned / financed assets |
Asset finance, leasing, corporate debt |
Residual value and charging integration |
| Industrial electrification |
Corporate-owned |
Capex, corporate debt, strategic co-investment |
Process integration and downtime risk |
| Microgrids / resilience systems |
SPV or hybrid |
Project finance, infrastructure capital, public support |
Monetizing resilience benefits |
| Grid-related infrastructure |
SPV / utility / developer |
Project finance, structured credit, public-private structures |
Permitting and long tenor risk |
| Multi-site decarbonization portfolios |
Portfolio vehicle or enterprise program |
Warehouse debt, portfolio finance, private credit |
Standardization across sites |
A major reason energy transition financing remains slow is not lack of capital. It is transaction friction.
Too many projects are presented in inconsistent formats. Too many sponsors approach investors who are not aligned by mandate, geography, stage, or ticket size. Too much time is wasted reworking materials that should have been investment-ready from the start.
That is where modern workflow infrastructure changes outcomes.
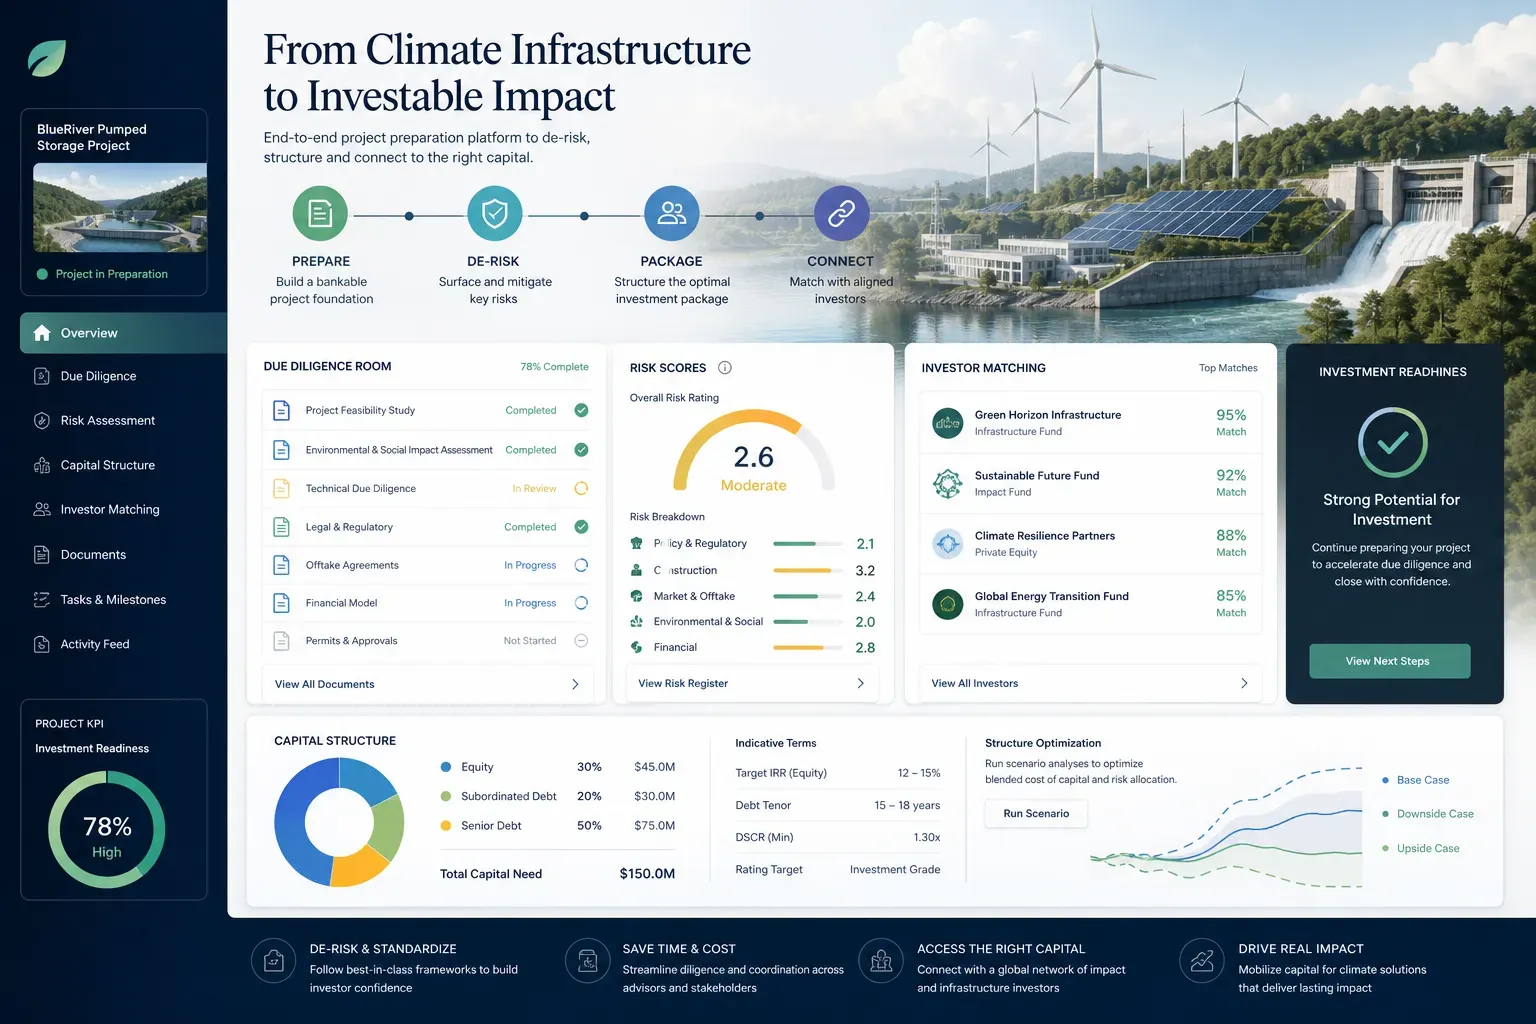
With Zero Circle, project owners and enterprises can benefit from:
This combination reduces dead-end outreach and helps serious projects reach relevant capital faster. For enterprises evaluating financing options, that can compress months of market friction into a more disciplined capital formation process. Teams looking for deeper support on structuring, underwriting logic, and transaction preparation can also use climate finance advisory and capital structuring support to move from concept to fundable deal materials.
Corporate decarbonization strategy is now unfolding in a more power-constrained world. Energy demand growth, especially from digital infrastructure, is reshaping financing priorities.
This matters for enterprises because decarbonization projects are no longer only about emissions reduction. They are increasingly about power access, reliability, and strategic control.
“Data center power demand currently accounts for between 1% and 2% of global power demand and is expected to grow by 165% through 2030 compared to 2023 levels.” - Neuberger Berman
For corporates with energy-intensive operations, especially those exposed to digital infrastructure growth, financing decisions must now account for both sustainability and energy security. That makes integrated planning across resilience, procurement, storage, and low-carbon supply even more valuable. It also makes sector-specific financing intelligence increasingly important in fast-growing areas like data center energy infrastructure.
Even sophisticated companies can weaken fundability by making avoidable errors.
Energy transition projects often have infrastructure-like characteristics. If they are evaluated only through short payback filters, strategic value is missed.
Early outreach without clean data, a coherent structure, or a clear ask can damage credibility.
Waiting until every issue is solved can also be a mistake. Many lenders and investors can help shape the structure if brought in at the right stage.
Not every capital provider finances every asset class, risk stage, or geography. Poor targeting slows the process and creates false negatives.
The farther a project moves from simple corporate capex toward structured finance, the more documentation quality matters.
A single site may be too small or inefficient to finance on its own. A portfolio of similar projects can attract better terms.
Is the goal lowest cost of capital, off-balance-sheet treatment, speed, flexibility, or strategic co-investment? Be explicit.
Do not bundle mature, cash-flowing assets with speculative ones unless there is a deliberate reason.
Translate technical scope into investment language: costs, returns, contracts, dependencies, downside cases, and milestones.
Separate what should be funded with equity, senior debt, tax-advantaged capital, public support, or lease-based financing.
Target by mandate, geography, check size, and asset preference, not by brand familiarity alone.
Have clear assumptions, supporting documents, and decision-ready materials before scaling outreach.
If capital is hesitant, diagnose whether the issue is structure, risk, stage, or materials. Do not assume the project is unfinanceable.
Advisory support is most useful not when it replaces internal ownership, but when it accelerates difficult parts of the financing process.
That includes:
The best advisory support is not theoretical. It should increase the probability of actual capital formation.
For enterprises, that can mean faster access to relevant investors, reduced underwriting friction, and stronger alignment between internal sustainability priorities and external financing realities.
There is no single best form of energy transition financing for corporates. There is only the structure that best fits the asset, the sponsor, the market, and the risk.
Balance-sheet funding may be right for some projects. Debt will remain the core tool for many. Project finance is powerful when revenues and risks can be ringfenced. Tax equity can unlock value in the right jurisdictions. Green banks and catalytic capital can bridge gaps where private markets alone are not enough.
But across all of these pathways, the same rule applies: projects get funded when they are legible, structured, and matched to the right capital.
That is where Zero Circle is built to help. We combine AI-driven scoring, investor matching, human-reviewed outreach, underwriting support, and capital structuring expertise to help projects and enterprises move from climate ambition to financeable execution.
If you are evaluating how to fund decarbonization, resilience, or energy infrastructure, now is the time to build a capital strategy that is as rigorous as the project itself.
Energy transition finance now sits inside corporate capital planning, not only with utilities and developers. Rising power costs, price volatility and demand from energy-intensive infrastructure such as data centers are driving it.
Project finance suits larger assets, such as utility-scale renewables, where the corporate wants to isolate risk in a special-purpose vehicle. It demands more preparation, because lenders underwrite the project's own contracts and cash flow.
Tax equity is relevant in the United States for renewable energy, storage and selected clean infrastructure because tax credits can be a large part of project value. It adds structuring complexity and is not a universal fit.
They support strategically important projects that private capital cannot yet underwrite alone, for example through subordinated capital. Public capital often works best as a bridge to private participation, not a replacement.
Fundable means investable under real market conditions, not perfect. Financiers need to know exactly what capital funds, what is complete, what remains at risk, and a credible revenue or savings model.