Energy Project Underwriting: What Lenders Need
Prepare for lender diligence with project finance advisors for energy transition: assemble revenue, permit, grid and construction evidence before outreach.
– 7 min read
Prepare for lender diligence with project finance advisors for energy transition: assemble revenue, permit, grid and construction evidence before outreach.

Bring a lender a project whose projected cash flow you can trace to contracts, technical work, approvals and a delivery plan. You can make contact before meeting every closing condition, provided you can identify what is secured, what remains conditional, who owns each open item and how a delay or downside case changes debt service.
Project finance advisors for energy transition can help you assemble and stress-test that case before outreach. The capital provider makes its own credit decision after legal, technical and financial diligence.
“Underwriting-ready” describes the quality of your evidence. It does not mean a lender has committed to finance the project. A bank or credit fund needs to see how you will build it, earn revenue and repay debt. A signed contract still raises questions if the model ignores one of its conditions; a marked draft with a realistic timeline and downside case can give the lender a clearer picture.
Start with a one-page deal snapshot: project company and sponsor, technology and location, development stage, requested capital and use of proceeds, target construction and operation dates, contracted versus exposed revenue, and the largest unresolved dependencies. Label each figure as actual, contracted, estimated or assumed. This gives a lender enough context to judge mandate fit before requesting a full data room.
For an introduction to debt, equity and project-company structure, see Renewable Energy Project Finance Basics. The task here is to support those financing choices with project-specific evidence.
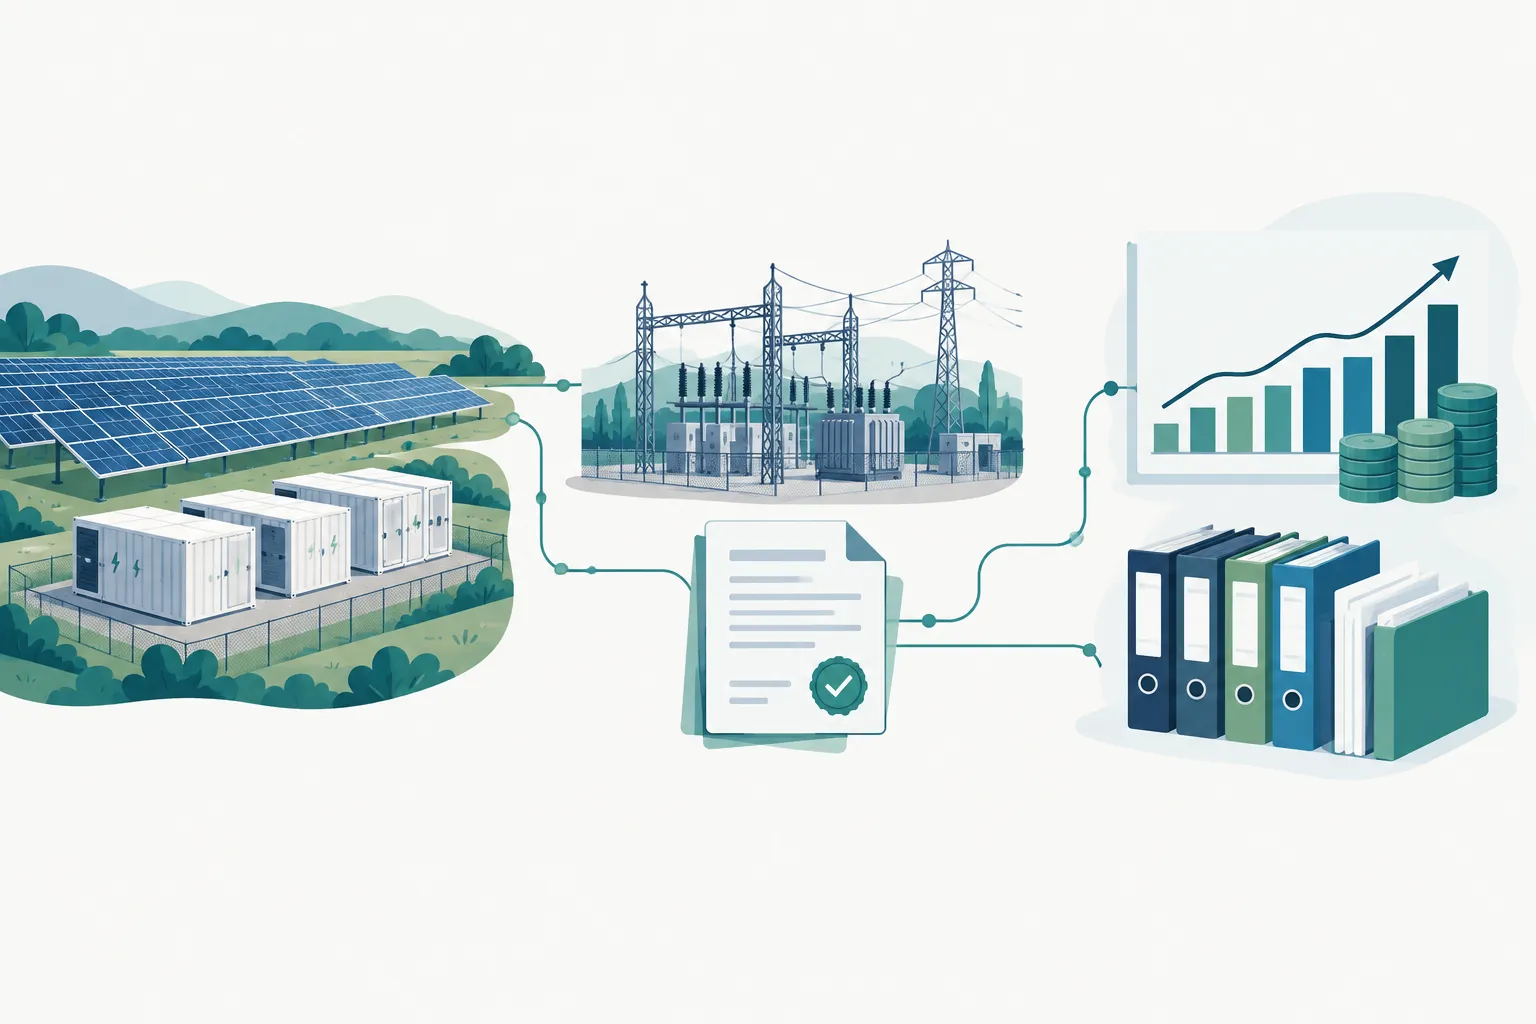
| Underwriting question | Sponsor-side evidence to assemble | Financial consequence to show |
|---|---|---|
| Who pays, for what and when? | Executed or draft offtake, capacity, tolling or other revenue agreements; pricing schedules; settlement and termination terms | Contracted cash receipts, merchant exposure, curtailment and delayed-start cases |
| Can the project legally occupy and operate its site? | Site-control documents, permit matrix, environmental work and outstanding approvals | Schedule slippage and mitigation costs |
| Can it connect and deliver output? | Interconnection status, studies and agreements, grid-upgrade scope, delivery milestones | Network costs, energization delay and output constraints |
| Can it be built to budget and date? | EPC or major supply terms, scope interfaces, schedule, contingency and security package | Cost overruns, delayed revenue and funding need |
| Will it perform over the debt term? | Independent resource or performance analysis, equipment terms, O&M scope and insurance plan | Generation or availability downside, operating costs and replacement reserves |
| Can the parties carry their obligations? | Ownership chart, sponsor track record, counterparty financial information and support documents | Default, replacement or credit-support scenarios |
"The PPA is key to bankability." - World Bank, Understanding Power Purchase Agreements
A lender will read past the headline price in a power purchase agreement (PPA). Put the executed agreement or current marked draft beside a plain-English summary of tenor, contracted volume or availability, price shape, escalation, delivery point, payment timing, curtailment, credit support, termination rights and conditions precedent. Separate the revenue streams if several counterparties pay the project.
Reconcile the contract to the monthly model lines. Show the share of output that remains uncontracted, the basis for merchant-price assumptions and what happens when generation falls or the offtaker pays late. For storage or flexibility projects, distinguish contracted revenue from forecasts based on market participation or dispatch performance. A forecast should remain labeled as a forecast.
Storage sponsors can also map revenue and performance assumptions against the project's operating role, as explained in battery storage projects.
Make a permit and land-rights matrix with authority or counterparty, application status, conditions, appeal or expiry exposure, responsible person and date needed on the critical path. Include environmental constraints and remediation work where relevant. Site control does not settle grid access, so document each risk separately.
Keep the interconnection package together: application and queue status, study findings, required upgrades, security obligations, milestones and any curtailment or congestion implications. Where the grid operator controls an upgrade needed for commissioning, carry its timing through the schedule and financing plan.
Reconcile the construction budget with the model and contractor scope. Identify exclusions, long-lead equipment, delivery milestones, change-order process, performance tests, liquidated damages if agreed, bonds or guarantees where applicable, insurance and the contingency owner. If several contractors divide the work, assign each interface to a named party.
For operations, document the production or resource assessment, expected degradation or availability, O&M responsibilities, major component replacement and insurance assumptions. An independent engineer may review the technical case during lender diligence; the sponsor can commission supporting work earlier, but it does not replace the lender's chosen review.
Create an ownership and contracting map from the project company through the sponsor, offtaker, EPC contractor, equipment suppliers, operator and any guarantor. Note assignment and step-in rights, consent requirements, security restrictions and related-party arrangements that could affect lender remedies. Record which contracts are signed, conditional or still being negotiated.
If your financing case assumes incentives, credit transfers or other support, isolate those proceeds and their eligibility or timing assumptions. Show a case without uncertain proceeds if they are material to repayment, and identify who bears the resulting shortfall.
A lender should be able to trace each major model input to its source and each material risk to its cash-flow effect. Build an assumptions register with source document, date, units, model cell or tab, owner and status. Use one timeline across development spend, debt draws, construction, commercial operation and repayment.
At minimum, give the capital provider a base case and clearly named sensitivities for lower output, higher capex, later commercial operation, weaker realized prices and higher operating costs. Show the effect on cash available for debt service, debt service coverage and any required additional equity or reserves. A model that maintains coverage only because an unsigned contract or unawarded permit is treated as certain is not ready to circulate.
Show timing conflicts. If the PPA start date assumes energization before the interconnection schedule allows it, correct the schedule or model the delay. List remaining conflicts where the lender can see them.
Suppose an interconnection milestone moves past the contracted delivery start. In the issue log, name the grid milestone and any PPA delay or termination exposure. Move first revenue in the model, then recalculate construction-period interest and debt coverage. A revised schedule alone leaves the lender with a contract summary and model that tell different stories.
Organize the data room around the credit team's questions. One workable index:
Keep an issue log alongside the files. For every unresolved item, record the decision needed, its owner, deadline, dependency, likely model impact and evidence that will close it. Version the model and material contracts together; when an offtake price or commissioning date changes, update the circulated model too.
For the first approach, send the snapshot and a limited set of supporting materials. As the lender's process advances, use a controlled data room for deeper legal and technical documents. That gives the credit team a diligence trail without circulating confidential files too broadly.
The World Bank's sample technical due-diligence scope for a wind project includes review of grid connection, power sales, construction schedule and potential cost overruns. Preparing a traceable record of these items makes subsequent specialist review more efficient; it does not dictate the scope any particular lender will require.
Judge an adviser or platform by the quality of the evidence trail it helps build and the fit of the investors it helps you reach. A “bankable” score by itself says little. The roles differ:
| Support | Useful sponsor-side contribution | What it cannot replace |
|---|---|---|
| Project finance adviser | Shape financing strategy, identify structural gaps, coordinate model and lender materials | Lender credit committee decision |
| Legal, technical and environmental specialists | Document title, contract, performance and site risks in their disciplines | The lender's independent diligence requirements |
| Workflow and matching platform | Standardize project data, track missing documents and prioritize capital providers by mandate | Signed contracts, permits or third-party verification |
| Lender or investor | Set its own terms, run diligence and make the investment or credit decision | The sponsor's responsibility for accurate disclosures |
Zero Circle combines project scoring, standardized project information, investor matching, underwriting support and human-reviewed outreach for energy and climate projects. You can use it to spot missing evidence and approach investors whose mandates fit your project's geography, stage and financing need. Its limitation: a platform score and a matched introduction do not constitute independent lender diligence or approval.
The sequence for finding suitable capital partners is explored in how to find climate project investors.
Ask a prospective adviser how it handles unsupported assumptions, who can edit the shared model, how it tracks document versions and who reviews outreach before it goes out. A broad promise of investor access will not answer those questions.
Approach lenders when you can explain the project, material assumptions and critical-path risks without contradicting your own files. An open permit or unsigned contract can still be part of an early conversation. A lender may discuss appetite and indicative structure, then reserve terms or commitment until it receives specified evidence.
Treat expressions of interest, indicative terms, internal credit sign-off and loan documentation as separate stages. An adviser can prepare materials and coordinate responses through those stages, but a proposed debt amount or draft term sheet is not a commitment to fund. Sponsor-side readiness should make the lender's diligence questions answerable, not pre-empt the lender's decision.
Use three statuses in the deal snapshot: secured (documented and effective), conditional (documented but subject to a stated event), and open (not yet evidenced). For each conditional or open item, add its expected resolution, the party responsible and the impact if it slips. If a central revenue source, grid path or land right has no credible path to resolution, work on that risk before broad lender outreach.
Bring a model, documents and risk register that agree with one another, and you give lenders a basis for a substantive conversation. Zero Circle can help organize that preparation and target relevant capital partners. The lender still decides whether to underwrite and approve the deal.