Resilience Finance: 7 Ways to Fund Climate Adaptation
Explore resilience finance through seven ways to fund climate adaptation, with guidance on repayment, project risk, insurance and blended capital.
– 7 min read
Explore resilience finance through seven ways to fund climate adaptation, with guidance on repayment, project risk, insurance and blended capital.
Resilience finance pays for projects that reduce damage from climate hazards, even when the project itself cannot charge everyone it protects. The financing choice starts with a simple question: Who receives the benefit, and what cash flow, if any, can pay for it? A flood barrier with no user fees needs a different capital stack from a water utility upgrading assets and collecting tariffs.
Project owners can waste time pitching investors who require cash flow the project cannot produce. Capital providers need to know whether the proposed protection comes with a credible payment plan.
UNDRR explains how resilience bonds can help finance adaptation:
Climate adaptation includes physical assets such as flood protection, water storage, cooling systems and grid hardening, as well as planning, monitoring and early-warning capabilities. A project can produce both public benefits, such as fewer disruptions across a city, and private benefits, such as lower repair costs for an asset owner. Those benefits do not automatically become cash available to service debt.
UNEP's 2025 assessment puts the scale of future demand in perspective:
"The report updates the cost of adaptation finance needed in developing countries, putting it at US$310 billion per year in 2035, when based on modelled costs." - UN Environment Programme
Separate three things before choosing an instrument:
An avoided-loss estimate supports the investment case. Lenders need a source of repayment; insurers need a defined risk and payout trigger. Each asks for different evidence.
| Approach | Best fit | Payment or return source | Risk it addresses |
|---|---|---|---|
| 1. Grants and technical assistance | Public-good projects and early project preparation | No repayment; funder budget | Development and affordability gaps |
| 2. Concessional capital and guarantees | Useful projects that cannot yet carry fully commercial terms | Project cash flow or public payments, with softer terms or credit support | Financing and credit risk |
| 3. Green or resilience bonds | Issuers with a credible repayment base and a portfolio of eligible investments | Issuer's pledged revenue or general obligations | Long-tenor capital needs |
| 4. Commercial project loans | Assets with predictable contracted revenue | Tariffs, offtake or service contracts | Construction and operating risk, subject to underwriting |
| 5. Public-private partnerships | Public services with measurable delivery obligations | User charges or public availability payments | Delivery and performance allocation |
| 6. Parametric insurance and insurance-linked structures | Acute hazard exposure and a need for rapid liquidity | Premiums fund contingent payouts | Residual event and liquidity risk |
| 7. Outcomes-based finance | Interventions whose results can be measured and paid for | Contracted outcome payer | Uncertain performance and adoption |
Each route solves a different funding problem. Insurance provides money after a covered trigger; it cannot pay the full upfront cost of protection. Grants can cover feasibility work while a loan funds construction. Identify the project's main constraint before combining the instruments.
Use grants where benefits are widely shared but no single beneficiary can be billed, such as neighborhood flood protection, wetland restoration or an early-warning system. They also pay for feasibility studies, hazard mapping, design and community engagement before a project is ready for debt.
Grant funding does not require repayment, though funders may impose eligibility, procurement and reporting conditions. Name the organization responsible for maintaining the asset after the grant runs out, and budget for that work.
Concessional loans offer terms that can make a socially valuable project viable when market-rate debt would strain its finances. A guarantee covers a defined part of a lender's risk where repayment is plausible but credit concerns block the loan. Neither fixes a project with no operating budget or payment source.
For a water network upgrade, a grant might fund design and a concessional loan might cover the portion that tariffs cannot support on market terms. State the subsidy needed, the reason for it and who ultimately repays the remaining capital. Blended climate project finance works best when the concessional layer changes a real financing constraint rather than merely reducing the sponsor's cost.
A bond can raise capital for drainage, cooling and resilient transport upgrades under one financing program. The issuer needs eligible projects, a way to track spending and the capacity to make ongoing payments. Calling the bond a resilience bond does not change its credit risk.
For a public issuer, the credit may rest on taxes or other pledged revenues. For a utility, it may rest on its operating cash flows. Investors need to distinguish the bond's credit risk from the environmental case for using its proceeds. Define eligible spending and report both allocations and adaptation outcomes.
A use-of-proceeds resilience bond is debt raised to pay for adaptation assets. It is not the same as an insurance-linked catastrophe bond, which transfers a specified disaster risk to investors and may release funds if its trigger is met.
Commercial lenders fit projects with a sufficiently predictable source of cash: a contracted service payment, regulated tariff or other enforceable revenue. Consider a utility raising financing to harden a substation. The lender will assess whether revenues and contractual protections cover construction, operation and debt service, not only whether the intervention reduces outages.
Underwriting should account for the design hazard, residual exposure after construction, insurance arrangements and who pays for repairs. Where neither customers nor a public agency can support payments, commercial debt will leave the funding gap open.
A public-private partnership, or PPP, can combine private delivery and finance with a public authority's long-term payment commitment. For example, a drainage system could be paid through availability payments tied to service standards. This works when outputs, maintenance duties and payment adjustments can be specified in a contract.
The public authority still needs a budget or revenue source. The delivery partner can manage construction and maintenance risk; the authority may need to retain policy and land-use risk. Contract terms determine who pays if performance falls short, and neither party can ignore the full cost of the service.
Parametric insurance pays when rainfall, wind speed or another agreed measure reaches a defined trigger. That lets a sponsor receive money for response and recovery without waiting for an assessment of every damaged asset. Insurance-linked structures can transfer defined catastrophe exposure to capital-market investors.
Basis risk is the trade-off: damage can occur without a payout if the trigger is missed, and a payout can occur when actual losses are smaller than expected. Design the trigger around the project's exposure and specify what the sponsor will do with the payout. Physical protection remains necessary.
For a sponsor, the cost is the premium or risk-transfer payment, not debt service on the insured asset. Budget for that recurring cost and for losses outside the cover's trigger, limit or period.
An outcomes-based contract pays for agreed results rather than reimbursing activity alone. A public agency or enterprise could, for example, commit to paying for a verified reduction in service interruptions. That promise of payment gives the project a potential financing source.
Before raising capital, agree on the baseline, measurement period, independent verification and payment formula. The contract must also say who absorbs the cost if results fall short. If you cannot credibly attribute avoided losses to the intervention, a grant or service contract may be easier to put in place.
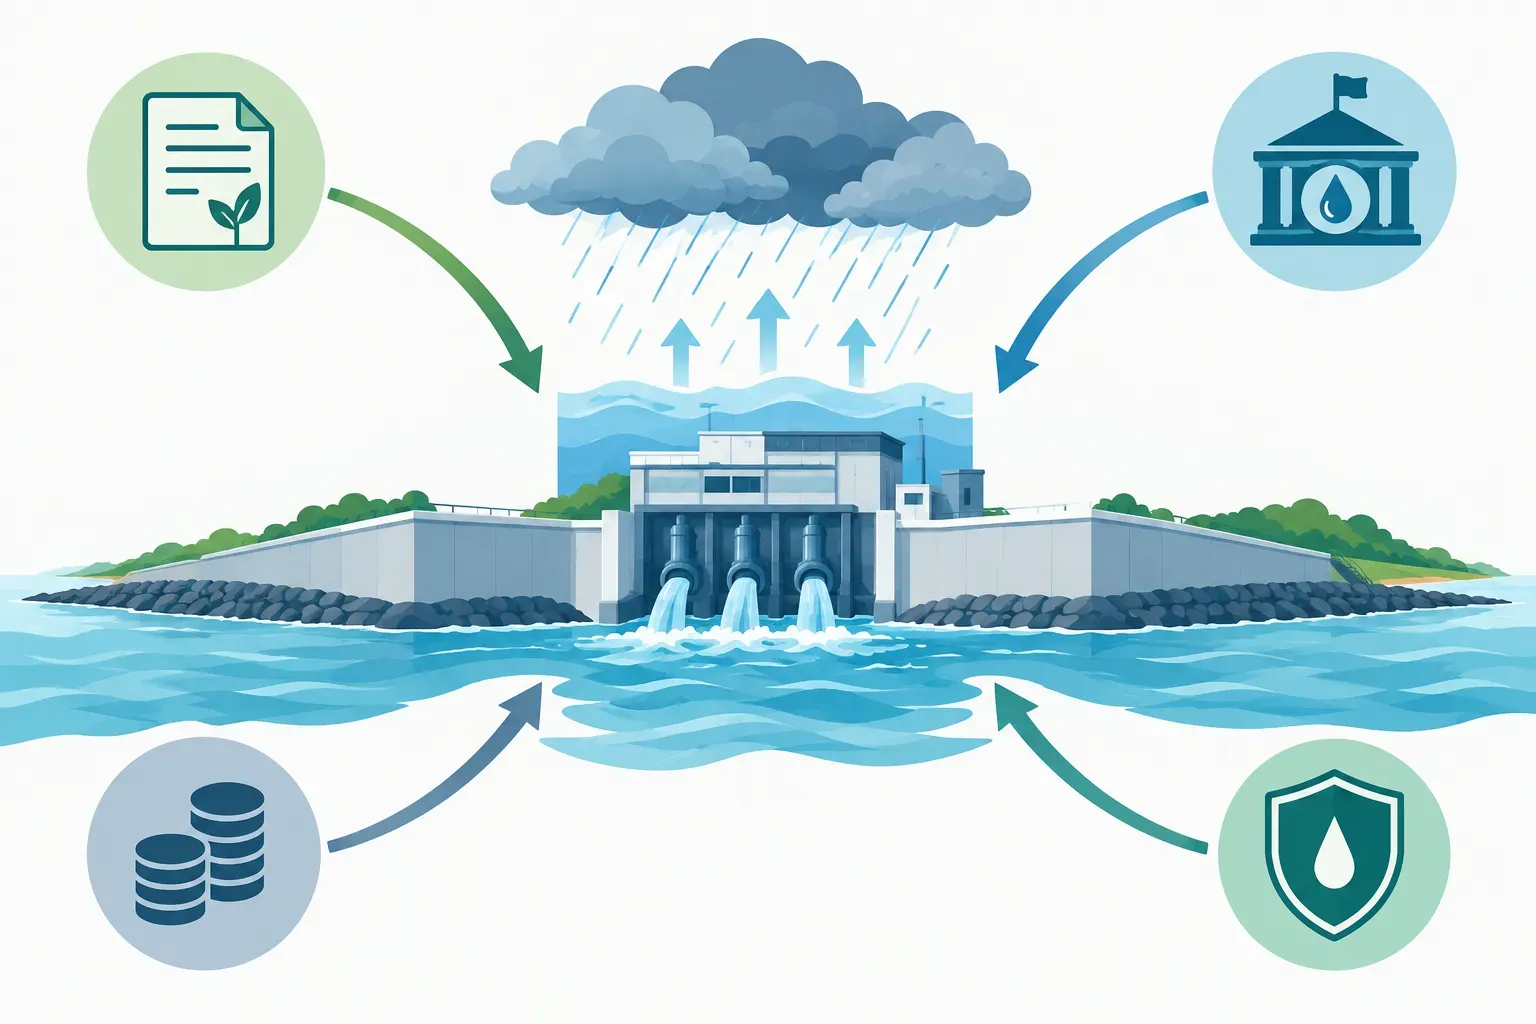
Suppose a coastal utility needs to protect a pump station from flooding. It has a direct interest in protecting its equipment, while customers benefit from uninterrupted service. Its funding stack could combine:
Sequence the funding around what the utility can prove and pay for. Preparation reduces uncertainty before borrowing; debt size follows payment capacity; insurance covers residual exposure. An insurance payout is contingent, and avoided losses are not cash available for routine debt service.
Give funders enough information to follow two paths: from the hazard and design to the expected protection, and from contracts or budgets to the proposed payments. A strong case needs both.
| Evidence | Question it answers |
|---|---|
| Site-specific hazard and exposure assessment | What can fail, and under which scenarios? |
| Engineering scope, schedule and cost estimate | What will be built and maintained? |
| Baseline and resilience indicators | What improvement will be measured? |
| Revenue, budget or committed payer | Who pays, when and from what source? |
| Contracts and risk allocation | Who covers delays, underperformance and residual losses? |
| Monitoring and reporting plan | How will the promised protection be demonstrated? |
Zero Circle helps owners package project information through scoring and capital-structuring workflows, then approach capital providers matched by geography, deal size and risk profile. The process works best once the owner can identify a payer or show why catalytic funding is needed. Investor matching still leaves engineering diligence and repayment questions to answer.
Choose resilience finance according to the project's payment source. Grants suit preparation and shared benefits; debt and bonds require repayment capacity; contracts need a committed payer; insurance addresses residual shocks. If your energy or climate infrastructure project has those pieces in view, Zero Circle can help organize the funding case and connect you with capital providers suited to its risks.
In climate project finance, resilience means the ability of an asset, service or community to withstand and recover from climate hazards. Resilience finance funds measures that strengthen that ability; the investment still needs a defined funding source or repayment path.
Resilience funding is capital for measures that reduce exposure, damage or disruption from hazards. It can come from grants, public budgets, loans, bonds, contracted payments or other sources, depending on who benefits and who can pay.
A resilience program is a coordinated set of activities to assess risks, prioritize interventions and track whether they reduce disruption or loss. Its financing may combine project preparation grants with capital for construction, maintenance and risk transfer.